

TL;DR: Neither OpenAI nor Anthropic has ARR. Each headline is the sum of five streams that renew differently, and the market is paying a recurring-revenue multiple on the sum.
The $70 billion was investors grossing OpenAI up onto Anthropic’s basis, not an OpenAI figure. The $50 billion is the company’s own number, net of partner sales.
Of the three business streams, the model call billed by the lab is a monthly tenancy, the call billed by a cloud is a tenancy on someone else’s shelf, and only the agent, the lab’s harness around its own model, can turn rent into ownership.
The 2025 numbers describe the chat-and-API era; agents earned the run rate the market is pricing. Neither lab has published retention, backlog, or the share of its revenue under a floor.
The ranking inverts the headline: the faster grower has the more exposed mix, with 47 percent of 2025 revenue billed by two clouds that sell its rivals.
That is why Codex against Claude Code matters more than whose run rate is bigger, and why the S-1’s split by stream and channel is the disclosure to read first.
The controversy over the Financial Times’s story last week about OpenAI’s revenue would be almost comical if it wasn’t so terrifying.
On October 8, the FT reported that OpenAI’s investors had been told by the company that its annualized revenue was approaching $50 billion, well below the $70 billion figure that had circulated just a couple of weeks earlier. A $20 billion revenue gap is substantial, so the market naturally sent the stock of companies like Nvidia, Oracle, and CoreWeave plunging. I even got a call from a colleague asking, “Did you see that?”
Yes, I did. But the reasons I found it shocking differed from most observers'.
The two numbers were never the same number. The $50 billion was OpenAI’s own figure: its annualized revenue at the end of September, on its own basis, which counts only the money it keeps. The $70 billion was not OpenAI’s figure (though the company has not publicly commented on either figure). As Axios noted, OpenAI’s investors grossed the company up to Anthropic’s basis, which books the full price of every sale made through Amazon or Google as Anthropic’s own revenue. The investors did it, no doubt, so that the two labs could be compared. By coincidence, the $70 billion is also close to OpenAI’s reported year-end target.
But $50 billion? $70 billion? Or $65 billion in ARR for Anthropic? It doesn’t matter, because none of those numbers are ARR.
Annual recurring revenue was invented for subscription software to describe one specific thing: a contract to pay a fixed amount for access to a product, known in advance, renewing by default, at a stable price. Those four properties are why a dollar of ARR earned a premium: the dollar came back on its own. The metric is an artifact of the SaaS Glory Days, and we've pressed it into service to describe businesses that bear almost no relation to what came before.
That is a classic mistake in a period of Discontinuity. Such periods, like the current generative and agentic AI Discontinuity, represent a clean break from the past, rendering historical precedents, traditional spreadsheets, and old benchmarks obsolete and meaningless. As I explain in Orchestration Economics, relying on old frameworks is dangerous because they interpret fresh evidence as confirmation of the regime that is ending.
In the case of the SaaS-era ARR benchmark, the labs’ revenue has almost none of those properties. Most of it is metered: customers pay by the token and can use more, less, or nothing next month. Where a commitment exists, it is a monthly spending floor for the term of a renewal, not a year of contracted revenue. You can replace the product behind the call by changing a string, so you re-win the revenue above the floor every month, call by call. And nearly half of Anthropic’s 2025 revenue was billed by Amazon and Google, which own the customer relationship and sell competing models from the same shelf.
Multiply that by twelve months to measure scale and momentum. It does not measure what revenue comes back to Anthropic. That is the difference between a run rate and ARR, and the market has been pricing the first as if it were the second.
This is why I use the metaphor “two tenants” to describe OpenAI and Anthropic. Their revenue is rent, paid month by month by customers who can switch. Their compute is a lease, signed for years with landlords who also sell to their rivals.
Analysts, investors, and markets understand this gap so poorly that it deeply troubles me. OpenAI and Anthropic are two of the most important companies for anyone trying to understand the next decade of business, and a market that has financed hundreds of billions of dollars of compute against their growth does not know how to read their revenue. That would be disturbing enough with Anthropic moving toward a potentially historic IPO in November. But the stakes are larger than a single listing.
The two labs sit at the center of a vast web of interconnected deals, the well-documented circular financing between infrastructure companies and suppliers such as Nvidia. If you can't read how they make money, you can't size the systemic risk around them. The market is beginning to sense this: debt anxiety around Oracle, SB Energy's delayed IPO, Firmus's withdrawn IPO, and the astronomical revenue projections floated to justify the spending. Without clarity, markets overreact, as we saw with the SaaSpocalypse earlier this year.
To be clear, I am not an AI alarmist writing to tell you that we are doomed. I have followed these two companies closely for two years, first in due diligence for clients and then as an investor building my own frameworks, and I remain extremely bullish on the long-term value of generative and agentic AI. But one of my fundamental goals with Decoding Discontinuity is to help people navigate a moment when the old models and benchmarks no longer serve them.
In that spirit, this article is the first of a three-part series designed to pierce some of these misunderstandings and clarify the nature of these businesses:
Part I: What the numbers mean: I examine what OpenAI and Anthropic’s headline ARR and run-rate figures measure, and how much of their revenue is durable.
Part II: What comes next: I model how AI work grows, how much still requires frontier models, and whether the labs or other platforms capture that work. That lets me estimate December 2027 run-rate revenue for OpenAI and Anthropic.
Part III: What it is worth: I value each revenue stream and trace the long-term compute commitments built around the labs, asking what happens if growth or control of the agent layer falls short.
First, look past the headlines and unpack the businesses inside them. Despite the obsessive comparisons between OpenAI and Anthropic, the two have very different customers, which means very different contracts and renewal prospects.
Is a run rate the same as ARR?
A run rate is a recent period of usage multiplied by twelve; it says nothing about what customers have committed to. While ARR gets thrown around loosely, Anthropic does not use it in its own announcements. Instead, its announcements use “run-rate revenue.” OpenAI does use ARR. Sarah Friar, its chief financial officer, wrote on the company’s site in January 2026: “$2B ARR in 2023, $6B in 2024, and $20B+ in 2025.” The press applies the label to both: CNBC and Axios both headlined OpenAI’s figures as “annual recurring revenue”, and the trackers behind every chart carry an ARR column.
The FT story split readers into two camps. One says the race is over, because Anthropic’s $65 billion July run rate placed it ahead of OpenAI. The other says Anthropic’s revenue is grossed up because every dollar sold through Amazon or Google is booked as Anthropic’s revenue, while OpenAI counts only what it keeps.
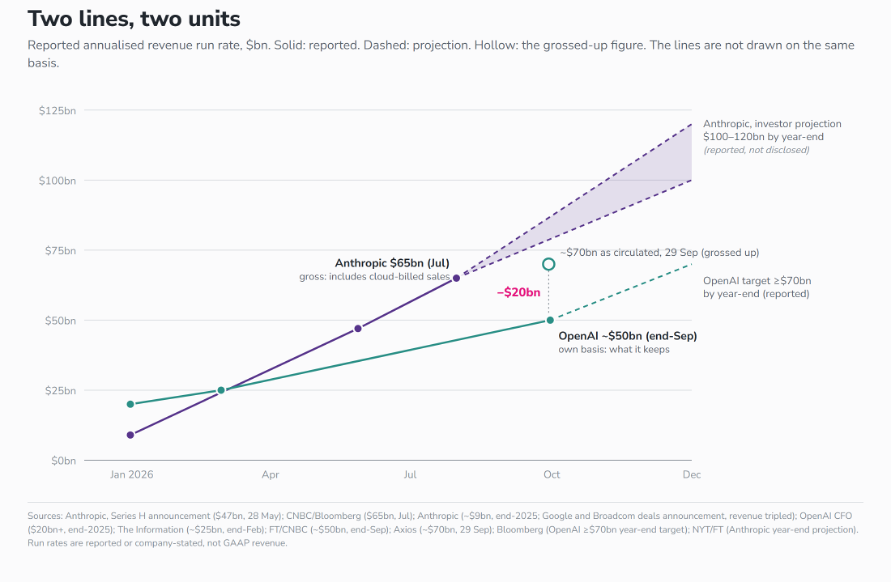
The label, either label, tells us how the number is presented, not what kinds of business it contains, how much is committed, or how likely customers are to keep spending. To answer that, we must unpack the streams inside each figure.